Digital technology in Burundi: Someone is doing a good job, but in the wrong direction
Burundi's latest digital payment regulation demonstrates something remarkable: our institutions are capable of producing world-class policy. But policy alone doesn't build industries. Innovation does. Are we solving tomorrow's problems before we've created today's opportunities? Here's why I believe Burundi needs regulatory sandboxes before more rulebooks.

A few days ago, I came across a facebook post announcing that Burundi central bank, the Banque de la République du Burundi (BRB) had released a new circular governing payment services within Burundi’s National E-commerce Ecosystem. Out of curiosity, and perhaps because technology is one of those subjects I cannot ignore, I downloaded the document.
Seventeen pages later, I found myself with two very different emotions.
a)The first was admiration.
The document is genuinely well written. Interoperability, fiduciary accounts, strong authentication, digital invoicing, someone clearly read the international playbook and translated it carefully into Burundian legal French. For lawyers, regulators and compliance officers, this document probably reads like poetry.
Every article is carefully structured. Every definition is precise. Every obligation is clearly articulated.
b)The second was disappointment.
Not because the regulation is wrong. It’s actually quite good. Comprehensive. Ambitious. Technically sound. And yet, after years working in fintech across Burundi, Europe and the US, I couldn’t shake one feeling: we are pouring enormous effort into solving a problem we don’t have yet.
Let me be clear before the outrage begins: I am not anti-regulation. Financial services touch people’s money and livelihoods, and money without oversight tends to disappear in creative ways. Regulation matters.
The problem isn’t regulation. It’s sequencing.
Imagine walking into an empty field and deciding the first thing it needs is traffic lights. Technically correct. Practically absurd. Before traffic lights, you need roads. Before roads, you need people actually travelling. Reading this circular felt like watching someone install a very elegant set of traffic lights in a field where, as far as I can tell, nobody has driven a car yet.
Which brings me to three things I think we’re getting wrong.
1. We’re benchmarking against the wrong chapter.
It’s tempting to look at London, Singapore, or the EU, admire their sophisticated financial rulebooks, and assume that writing similar rules is step one toward a modern digital economy. It isn’t. Those countries wrote their rulebooks after hundreds of fintech companies had already spent years testing products and burning investors’ money. We’re copying the final chapter of someone else’s story without reading the first ten.
And technology doesn’t wait politely while we catch up. Five years ago AI lived in research labs. Now it approves your loan and possibly writes better code than you do. So, genuine question: who inside Burundi’s institutions wakes up every morning specifically to track where this is all heading? I don’t know. And that gap worries me more than any single clause in this circular.
2. We’re regulating innovation before we’ve allowed any to exist.
Nobody wrote Facebook’s regulations before Facebook existed. Nobody drafted taxi law for Uber before someone wondered if a private car could be a taxi. The technology always shows up first. The rulebook shows up later, sometimes years later, looking slightly out of breath.
Kenya didn’t have a bespoke legal framework ready when M-Pesa launched in 2007. Regulators let it run, watched carefully, and adjusted as they learned. Today Kenya is a global reference point for mobile money. Imagine instead if Safaricom had been told to first behave like a fully licensed commercial bank. We’d probably still be waiting.
Now picture a twenty-four-year-old in Musaga who’s spent eight months building a payment app on a second-hand laptop and Wi-Fi with opinions of its own. Before he can test it with twenty local shops, he’s expected to produce governance frameworks, compliance documentation, cybersecurity policies and capital reserves, the paperwork of an institution that’s existed for decades. He hasn’t onboarded a single customer yet.
That’s not caution. That’s asking someone to build the plane’s maintenance manual before they’ve built the plane.
3. We invest more in writing rules than in the people meant to break them (productively).
Regulations can be amended. Institutions can be reshuffled. Human talent, once discouraged, doesn’t come back so easily.
Ask yourself: where is Burundi’s national fintech competition? Where’s the BRB Innovation Challenge? The startup grants, the accelerators, the scholarships sending young engineers to spend six months inside a Kenyan or Nigerian fintech before coming home to build something here? I’ll wait.
Software has a wonderful property: it doesn’t need a shipping container or a border post. A developer in Bujumbura can write code used in Nairobi by lunchtime. That should completely change how we think about economic development, yet we still spend most of our energy asking “how do we regulate this?” instead of “how do we produce more of the people who’ll build it?”
The fix is almost embarrassingly simple: build a sandbox.
Not the plastic kind, although the metaphor holds. In a sandbox, children build, collapse, and rebuild castles without anyone calling the police. A regulatory sandbox applies the same logic to fintech: startups get a controlled space to test products on a limited number of real customers, under supervision, with reduced (not absent) requirements, while regulators watch and actually learn something instead of guessing from behind a desk.
The UK’s Financial Conduct Authority launched exactly this in 2016. It didn’t demand every startup behave like Barclays on day one. It let companies test, report, and grow inside supervised limits, and that philosophy quietly helped London become one of the world’s fintech capitals.
Here’s the part people usually miss: a sandbox is not a discount on regulation. It’s a different regulatory instrument entirely, built for a situation where nobody, not the founder, not the regulator, actually knows yet how the product will behave once real humans start using it.
Full licensing assumes the risks are already understood and simply need to be managed. A sandbox assumes the risks haven’t even been discovered yet, and the fastest way to discover them safely is to let a small, contained version of the thing exist in the real world, under supervision, before anyone bets the national payment system on it.
So what would this actually look like in Bujumbura?
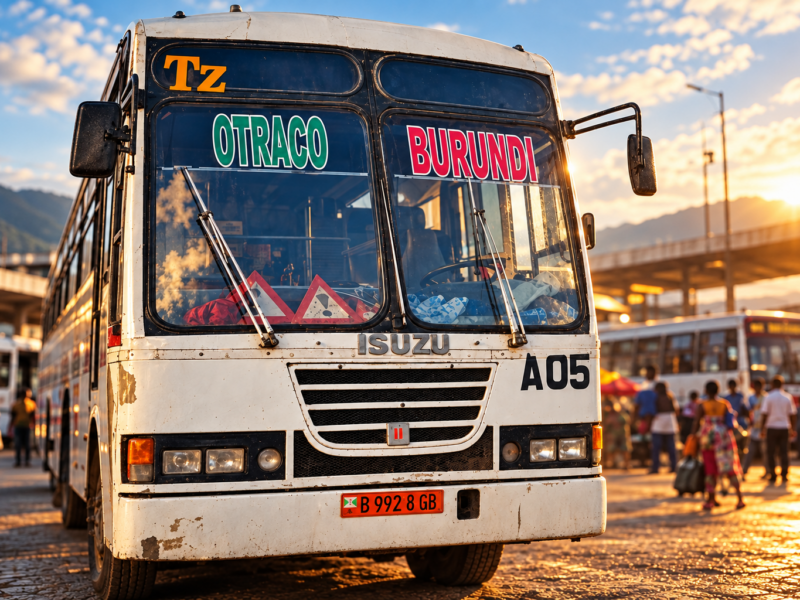
Say a small team builds an app letting minibus operators accept digital fares instead of loose change that mysteriously evaporates by the end of the day. Under today’s rules, they’d need to satisfy requirements built for institutions moving billions of francs, before confirming a single driver wants to use the thing.
Under a sandbox, the BRB instead grants them, say, six months to test with fifty minibuses in one commune. Transaction values are capped. Reporting is monthly, not annual. If drivers start double-charging passengers or the app quietly loses money in the queue, the BRB sees it early, at a scale where the damage is a bad afternoon, not a national headline.
If the pilot works, the founders graduate toward a full license already knowing which parts of their compliance file matter and which parts are decorative. If it doesn’t work, nobody’s savings evaporate, no minister has to explain anything in parliament, and the founders walk away with something more valuable than a certificate: they know, precisely, why it failed.
Multiply that by twenty pilots a year, payments, micro-insurance, agricultural finance, remittances and within three years the BRB isn’t regulating theories anymore. It’s regulating businesses it has personally watched grow up, fail, or occasionally surprise everyone.
Imagine the BRB running the same thing: twenty startups a year, a competitive selection panel, twelve months of supervised testing, capped transaction volumes, quarterly check-ins. Some fail, good, that’s data, not disaster. A few succeed, graduate into full licensing, and Burundi ends up regulating a proven business instead of a hypothetical one.
Now imagine our developer in Musaga getting that chance instead of a stack of compliance forms. Multiply him by fifty. That’s an ecosystem. One circular, however well written, is not.
The BRB has just proven it can write regulation at an international standard. Genuinely impressive. The next, harder question is whether we can build something worth regulating in the first place, because rulebooks protect industries.
They don’t create them.
People do.